A Legal Vacuum, a Vanishing Target, and the Quiet Conversion of Citizens into Creditors
By Louis ‘Barok‘ C. Biraogo | October 16, 2026
THE numbers are impressive. The press releases are triumphant. The interest rate is attractive. And that, dear reader, is precisely what should terrify you.
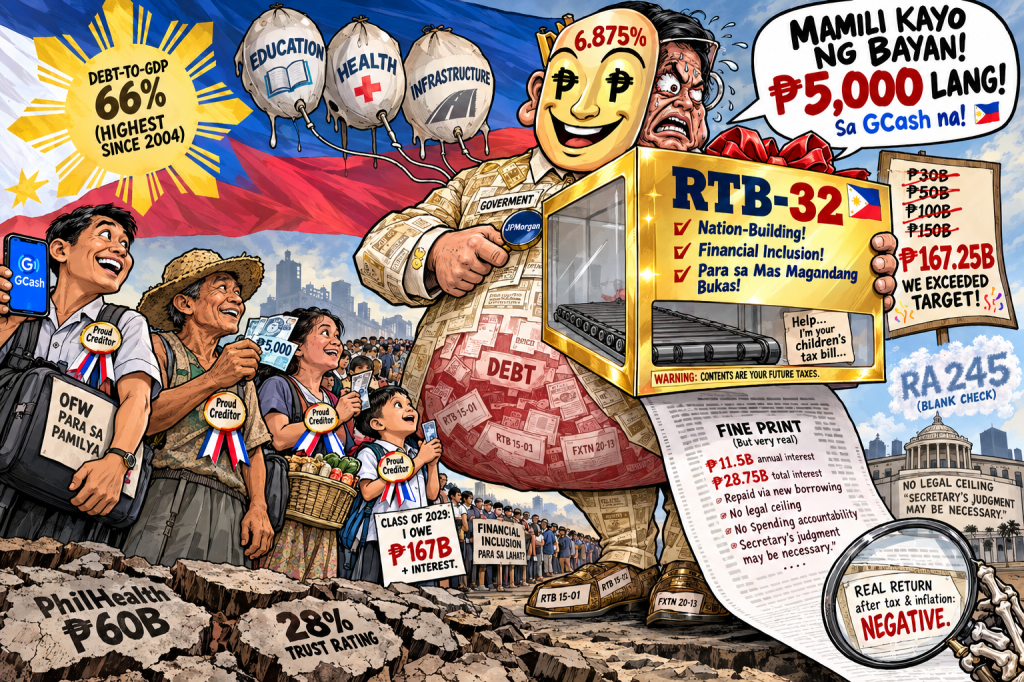
On October 9, the Bureau of the Treasury (BTr) announced it had raised ₱167.25 billion from the sale of Retail Treasury Bonds 32—exceeding its target, marketing the offering to millions of ordinary Filipinos through their mobile phones, and framing the entire exercise as an act of financial inclusion and nation-building.
But beneath the celebratory headlines lies a more troubling reality: a government drowning in debt, borrowing from its own citizens at a rate that exceeds sustainable growth, with virtually no legal constraint on how much it can borrow or how it spends what it takes.
The Philippine government is not selling you an investment. It is selling you a share of your own future obligations.
The Arithmetic of Desperation
Let us begin with the fundamentals, because the fundamentals are rarely included in the marketing materials.
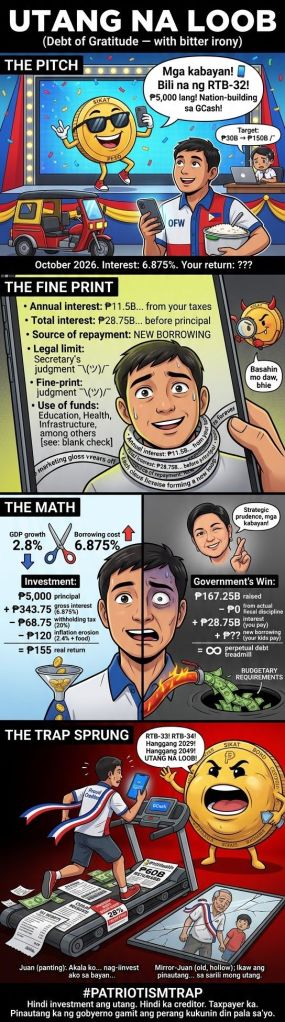
The government raised ₱167.25 billion. The coupon rate is 6.875 percent. That means the annual interest bill on this single issuance is approximately ₱11.5 billion. Over the 2.5-year life of the bond, the government will pay roughly ₱28.75 billion in interest alone—before a single peso of principal is returned.
Where does that money come from? From you. From your taxes. From your children’s taxes. From the economic growth that the government keeps promising will materialize, though the International Monetary Fund (IMF) now projects government debt will hover around 60.2 percent of GDP, while the actual figure hit 66 percent in the second quarter of 2026—the highest since 2004.
The math is not subtle. The Philippines is borrowing at 6.875 percent while its economy grew at a pathetic 2.8 percent in the first quarter, the weakest pace since the pandemic. When your borrowing cost exceeds your growth rate, you are not managing debt. You are perpetuating it.
This is not a temporary anomaly. The national government’s outstanding debt reached ₱19.61 trillion as of August 2026, with the debt-to-GDP ratio expected to remain above 60 percent through 2027 and only marginally declining to 58-61 percent by the time President Marcos leaves office in 2028.
The government’s own projections assume everything will go right. Everything rarely does.
The Vanishing Target
Here is a detail that should trouble even the most credulous observer: the Treasury originally set a target of ₱30 billion for this offering.
That is not a typo. Thirty billion pesos.
The target was then raised to ₱150 billion during the launch, and the final tally came in at ₱167.25 billion. The headline reads “exceeds target”—technically true, but only if you ignore that the target was quintupled midstream to accommodate investor demand.
This is not fiscal discipline. This is a government that decided how much it wanted to borrow and then changed the goalposts to match the outcome.
Worse, this offering represents a 61 percent decline from last year’s RTB issuance, which raised ₱425.51 billion. National Treasurer Sharon Almanza has acknowledged that the government deliberately scaled back the size “amid elevated yields.” Translation: the market is demanding a premium to lend to this government, and the government blinked.
The official narrative frames this as strategic prudence. The reality is that the Philippines is paying more to borrow less, and calling it success.
The Legal Vacuum
If you want to understand why Philippine governments can borrow with such abandon, you need to look at the law—or rather, the absence of meaningful law.
The primary statute authorizing government borrowing is Republic Act No. 245 (The Government Borrowing Authority Act), enacted in 1948 and amended by Presidential Decree No. 142. Section 1 of this law authorizes the Secretary of Finance, with the President’s approval, to borrow “such sum or sums as in his judgment may be necessary.”
Read that phrase again: “as in his judgment may be necessary.”
There is no debt ceiling. No borrowing cap. No statutory limit tied to GDP or revenue. The Secretary of Finance can borrow whatever he deems necessary, and the only check is the President’s signature—hardly a meaningful constraint when the President controls fiscal policy.
The 1987 Constitution of the Republic of the Philippines offers no additional protection for domestic borrowing. Article VII, Section 20 requires Monetary Board concurrence only for foreign loans. Article VI, Section 24 requires debt bills to originate in the House, but the actual issuance of government securities has been delegated to the Executive through decades of practice and statutory interpretation.
This is not an oversight. It is a structural feature of Philippine governance: the Executive can borrow without meaningful legislative oversight, then spend the proceeds on vaguely defined “budgetary requirements” with minimal accountability.
The RTB-32 proceeds will support “education, health, infrastructure, agriculture, among others.” That is not a use-of-proceeds disclosure. That is a blank check.
The Patriotism Trap
Now we come to the most insidious aspect of this entire operation: the deliberate targeting of ordinary Filipinos, overseas workers, and small savers as the buyers of government debt.
The minimum investment is ₱5,000. The bonds can be purchased through GCash, PDAX, Landbank’s mobile app, and other digital platforms. The Treasury conducted roadshows in Baguio, Batangas, Cagayan de Oro, Cebu, Davao, Iloilo, Naga, and Pampanga, and held financial literacy sessions for overseas Filipino communities.
On its face, this looks like financial inclusion. A government security previously available only to institutional investors is now accessible to the masses. What could be wrong with that?
Everything, if you look closely.
First, the interest rate. At 6.875 percent, the gross annual return on a ₱5,000 investment is ₱343.75. After the 20 percent final withholding tax on interest income, the net return is approximately ₱275 per year. With inflation running at 2.4 percent as of February 2026—a 13-month high—and food inflation even higher, the real return on this investment is minimal or negative.
You are lending money to the government at a rate that barely keeps pace with the rising cost of rice.
Second, the tenor. This is a 2.5-year bond, maturing in April 2029. That is not short-term. Investors who need their money before maturity must sell in the secondary market, where prices fluctuate and liquidity is uncertain. Most retail investors, as the government itself acknowledges, hold bonds to maturity. They are locked in.
Third, the framing. The government markets these bonds as “nation-building”—a patriotic act of lending to your country. This is emotional manipulation dressed as civic duty. You are not building the nation. You are financing its deficits, at a rate that benefits the government more than it benefits you.
And the government knows exactly who it is targeting. The inclusion of OFBank’s mobile app and financial literacy sessions for overseas Filipino communities is not accidental. Overseas Filipino workers send home over $30 billion annually. They are financially unsophisticated but deeply patriotic, and the government has identified them as a captive market for its debt.
The RTB program effectively monetizes diaspora loyalty.
The Bond Switch Shell Game
There is another element of RTB-32 that deserves scrutiny: the bond exchange program.
Holders of five existing securities—RTB 15-01, RTB 15-02, RTB 05-15, FXTN 20-13, and FXTN 03-30—were offered the opportunity to exchange their maturing bonds for the new RTB-32 issuance.
The Treasury has not yet announced how much was raised through this exchange component. That silence is telling.
When a government exchanges maturing bonds for new ones, it avoids a cash outflow. The investor’s principal is not returned; it is rolled over into a new obligation. The government’s debt does not decrease—it is merely refinanced at a longer maturity.
For the government, this is a convenient way to manage refinancing pressure without acknowledging it. For the investor, it extends exposure to a government whose fiscal trajectory is deteriorating.
The exchange is voluntary in form. But when the alternative is receiving cash that must then be reinvested in an uncertain market, many investors will choose the path of least resistance. The government is counting on that inertia.
The Index Inclusion Mirage
The final piece of this puzzle is the government’s parallel announcement that it will adopt international bond pricing conventions effective January 4, 2027, ahead of the Philippines’ inclusion in JPMorgan’s Government Bond Index–Emerging Markets (GBI-EM) on January 29, 2027.
This is presented as a technical reform that will lower borrowing costs by attracting foreign investors. The Finance Secretary calls it “aligning with international standards.” The Bangko Sentral ng Pilipinas (BSP) Governor says it will deepen the capital market.
What the press releases do not emphasize is that index inclusion does not guarantee lower borrowing costs, nor does it guarantee that foreign capital will flow in at the rates the government needs.
The Philippines will receive a projected 1.78 percent weight in the GBI-EM, with nine eligible bonds worth approximately $49 billion. That is modest. More importantly, index inclusion makes Philippine bonds more sensitive to global risk sentiment. When emerging market sentiment sours—as it inevitably will—foreign investors can exit quickly, amplifying volatility.
The government is trading a degree of monetary autonomy for the hope of lower yields. That is not a bargain; it is a gamble.
And the timing is suspicious. The pricing convention change and index inclusion are scheduled for January 2027—conveniently positioned before the 2028 election cycle, when the administration will need to fund visible projects and maintain an economic growth narrative.
The government is not modernizing the financial system. It is setting the stage for a pre-election borrowing spree.
The Corruption Context
We cannot discuss Philippine government borrowing in isolation from the governance failures that have defined this administration.
The Supreme Court ordered the return of ₱60 billion in Philippine Health Insurance Corporation (PhilHealth) reserve funds that had been improperly transferred to the National Treasury—a unanimous ruling in Pimentel III et al. v. House of Representatives et al. that exposed the government’s willingness to raid social insurance funds to plug fiscal gaps.
Public trust in the administration has collapsed. President Marcos’ trust rating fell to 28 percent and his approval rating to 29 percent in the June 2026 Pulse Asia survey, with inflation and corruption identified as the primary drivers of dissatisfaction. A separate Pulse Asia survey found that 69 percent of Filipinos disapprove of the government’s handling of inflation, and 68 percent disapprove of its handling of graft and corruption.
This is the government that is asking you to lend it ₱167.25 billion.
What Should Be Done
The recommendations are straightforward, though politically difficult:
For policymakers: Enact a statutory debt ceiling tied to GDP or revenue. Require specific, project-level disclosure of how borrowed funds will be used. Establish an independent Debt Management Office separate from the Bureau of the Treasury, with reporting requirements to Congress.
For regulators: Strengthen oversight of government securities marketing to retail investors. Mandate clear, standardized disclosure of real returns after inflation and taxes. Require digital platforms to provide prominent risk warnings, not just convenient subscription buttons.
For civil society: Monitor the use of RTB-32 proceeds through Freedom of Information (FOI) requests and budget tracking. Build independent financial literacy programs that are not funded or managed by the government that benefits from bond sales.
For ordinary Filipinos: Understand that a government bond is not a patriotic gift. It is a loan. Before you lend, ask yourself whether the borrower has demonstrated the fiscal discipline to repay. The evidence suggests it has not.
The Bottom Line
The Philippine government has successfully borrowed ₱167.25 billion from its own citizens. It will pay approximately ₱28.75 billion in interest over the life of the bond. The principal will be repaid in 2029, likely through new borrowing.
This is not financial innovation. This is a debt treadmill, marketed as opportunity.
The government’s debt-to-GDP ratio is at a 22-year high. Its growth rate is anemic. Its legal framework imposes no meaningful borrowing limits. Its credibility is damaged by corruption scandals and constitutional violations.
And it is asking you to lend it money at a rate that barely covers inflation.
The Treasury calls this “financial inclusion.” A more accurate description would be “mass domestication of debt”—converting citizens into creditors of a government that has shown little inclination to live within its means.
The ₱167.25 billion is real. So is the obligation to repay it.
The question is not whether the government can borrow. It clearly can.
The question is whether it should be borrowing from you.
Louis ‘Barok’ C. Biraogo writes the Kweba ni Barok blog, covering Philippine politics, economics, and governance. This analysis is based on publicly available information as of October 10, 2026, and does not constitute financial advice.
Key Citations
A. Legal & Official Sources
· The 1987 Constitution of the Republic of the Philippines. Official Gazette of the Republic of the Philippines, 1987, http://www.officialgazette.gov.ph/constitutions/1987-constitution/.
· Republic Act No. 245. An Act Authorizing the Secretary of Finance to Borrow to Meet Public Expenditures Authorized by Law, and for Other Purposes. 1948, lawphil.net/statutes/repacts/ra1948/ra_245_1948.html.
· Presidential Decree No. 142. Amending Republic Act No. 245 Entitled “An Act Authorizing the Secretary of Finance to Borrow to Meet Public Expenditures Authorized by Law and for Other Purposes.” 1973, lawphil.net/statutes/presdecs/pd1973/pd_142_1973.html.
· Pimentel III et al. v. House of Representatives et al. G.R. Nos. 274778, 275405 & 276233. Supreme Court of the Philippines, 3 Dec. 2025, lawphil.net/judjuris/juri2025/dec2025/gr_274778_2025.html.
B. News Reports
· Mateo, Janvic. “More Pinoys Disapprove of, Distrust Marcos – Pulse.” Philstar.com, 21 July 2026, http://www.philstar.com/headlines/2026/07/21/2543522/more-pinoys-disapprove-of-distrust-marcos-pulse.
· “Philippine Debt-to-GDP Ratio Rises to 66% in Q2, Highest since 2004.” BusinessWorld Online, 7 Aug. 2026, bworldonline.com/economy/2026/08/07/768836/philippine-debt-to-gdp-ratio-rises-to-66-in-q2-highest-since-2004/.
· “DOF, BTr, BSP Welcome PH Gov’t Bonds Inclusion in J.P. Morgan’s Government Bond Index – Emerging Markets Series.” Philippine Information Agency, 22 Apr. 2026, pia.gov.ph/press-release/dof-btr-bsp-welcome-ph-govt-bonds-inclusion-in-j-p-morgans-government-bond-index-emerging-markets-series/.
· “Gov’t Raises P167.25B from New Retail Bonds.” Inquirer Plus, 10 Oct. 2026, plus.inquirer.net/business/govt-raises-p167-25b-from-new-retail-bonds/.
· Maligro, Tatiana. “Higher Food Prices Push Inflation Up to 2.4% in February 2026.” Rappler, 5 Mar. 2026, http://www.rappler.com/business/inflation-rate-philippines-february-2026/.
- ₱9 Billion in ‘Savings’? DILG’s Fire Truck Deal Smells Like Smoke
- ₱8B BBM Pork: CCTV for Every Captain’s Kumpare?
- ₱8.9 Billion, 331 Ghost Police Stations: The TIKAS Scandal Explained

- ₱8.4 Billion, 42,000 Barangays, 1 Election: The “Bawat Barangay Makikinabang” Vote-Buying Masterclass
- ₱75 Million Heist: Cops Gone Full Bandit

- ₱6.77B Ghost Haunts Duterte: RTC Dismisses Mans Carpio’s Desperate Plea
- ₱6.77 Billion and Zero Cash: The Sara Duterte SALN Math That Doesn’t Add Up
- ₱6.7-Trillion Temptation: The Great Pork Zombie Revival and the “Collegial” Vote-Buying Circus

- ₱58.53B, Zero Receipts: The LGSF Pork Barrel Nobody Wants to Name
- ₱53 Million Man Tells ₱695-a-Day Workers to Stop Being ‘Mayabang’: The Audacity of BSP’s Remolona
- ₱4.4 Billion and a Witness Who Can’t Explain It: The Duterte Impeachment’s Most Expensive Non-Answer
- ₱3.06 Billion for Evacuation Centers—But Nobody Knows Where They’ll Stand (Or If They’ll Exist)


Leave a Reply